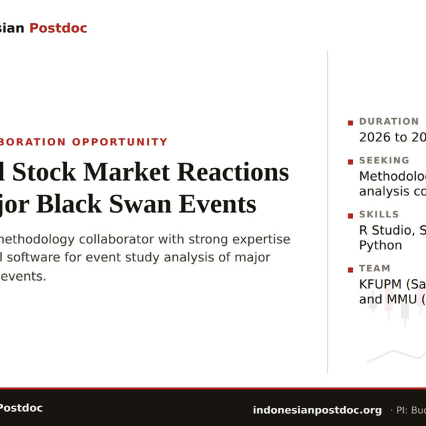
This project examines global stock market reactions to major black swan events using event study methodology. We are seeking a collaborator with strong expertise in statistical software, including R Studio, Stata, or Python, for event study analysis. Project duration: 2026 to 2027. Current team includes researchers from King Fahd University of Petroleum and Minerals (KFUPM), Saudi Arabia, and Multimedia University (MMU), Malaysia.
Researchers interested in joining this project are invited to send their CV, including a list of publications, to budi.setiawan@kfupm.edu.sa.
Please use the following email subject: Research Opportunity by Indonesian Postdoc: [Your Name]